Industrialisation of Fund Reporting: Why UCITS Annex IV should trigger an Operating Model Rethink
UCITS Annex IV will require firms to rethink how fund data is owned, controlled and used across the operating model. Firms are not starting without a foundation: much of the underlying data already exists across UCITS management companies (ManCos), investment managers, administrators and other service providers. The immediate task will be to bring those dispersed inputs into a controlled, consistent and explainable reporting process for which the ManCo can take accountability. In doing so, UCITS Annex IV can become a catalyst for overdue investment in the historically fragmented UCITS fund data and reporting model, with benefits that extend beyond the filing itself.
This is not only a compliance or fund reporting change. UCITS Annex IV forms part of a wider strategic shift in the UCITS regime. Investment firms and fund groups should therefore consider it within their product, distribution and operating-model strategy, rather than treat the resulting investment as a stand-alone compliance cost. That wider context matters for four reasons:
- Savings and Investments Union (SIU): the EU wants more household savings to support investment through capital markets, increasing the strategic importance of accessible and trusted fund products.
- Retail Investment Strategy (RIS): related proposals will increase transparency and scrutiny of retail investor outcomes and costs, reinforcing the need for efficient and well-controlled fund operations.
- Evolution of eligible assets: possible changes to the UCITS eligible-assets framework could broaden the range of instruments and strategies available, adding further data and operational complexity.
- UCITS credibility: as the regime expands and evolves, its global standing will continue to depend on strong oversight, reliable data and investor protection.
Together, these developments make the quality of fund data part of the future UCITS proposition. Annex IV is the immediate catalyst, but the strategic issue is whether firms use it to build a stronger and more adaptable operating foundation.
From fragmented reporting to data-led supervision
The supervisory journey starts from a patchwork of returns introduced at different times, for different purposes and across different jurisdictions. For UCITS, national supervisory returns, statistical reporting, specialist regimes and ad hoc requests provide useful information, but not a single EU-wide dataset that can be analysed consistently across funds and markets.
AIFMD Annex IV established a more granular model for alternative investment funds. Extending Annex IV-style reporting to UCITS now creates the basis for a broader supervisory dataset, while ESMA’s integrated funds reporting work seeks greater consistency in definitions, collection and regulatory use across both regimes.
The objective is to support a more continuous and risk-based supervisory model. Granular, comparable data can help national competent authorities and ESMA identify outliers, assess liquidity and leverage, monitor concentrations and interconnectedness, and target follow-up work more effectively. Harmonised reporting is therefore an enabling layer for data-led supervision, not simply a common template.
The fund data model has not kept pace
That model has persisted for understandable reasons. Reporting obligations have grown incrementally, often regulation by regulation, jurisdiction by jurisdiction and report by report. No single party has owned the full economic case for rebuilding the fund data model. The benefits of cleaner data, automation and workflow improvement are spread across the value chain, while the cost and disruption of change sit with specific firms, teams or service providers.
If the existing model could produce the required outputs, even with friction, the strategic case for change was easy to defer. Fragmentation became embedded because it was cheaper in the short term than redesigning the operating model.
What UCITS Annex IV will involve
Against that backdrop, the practical question is how the new EU framework will interact with the returns that UCITS already submit in individual jurisdictions. Greater consistency and rationalisation are intended, but the final technical standards and implementation arrangements will determine which national requirements are replaced, retained or incorporated. The detailed template and field definitions remain under development, although reporting is expected to cover the markets and instruments in which each UCITS trades, its principal exposures and concentrations, and the information supervisors need to monitor liquidity, leverage, interconnectedness and potential systemic risk.
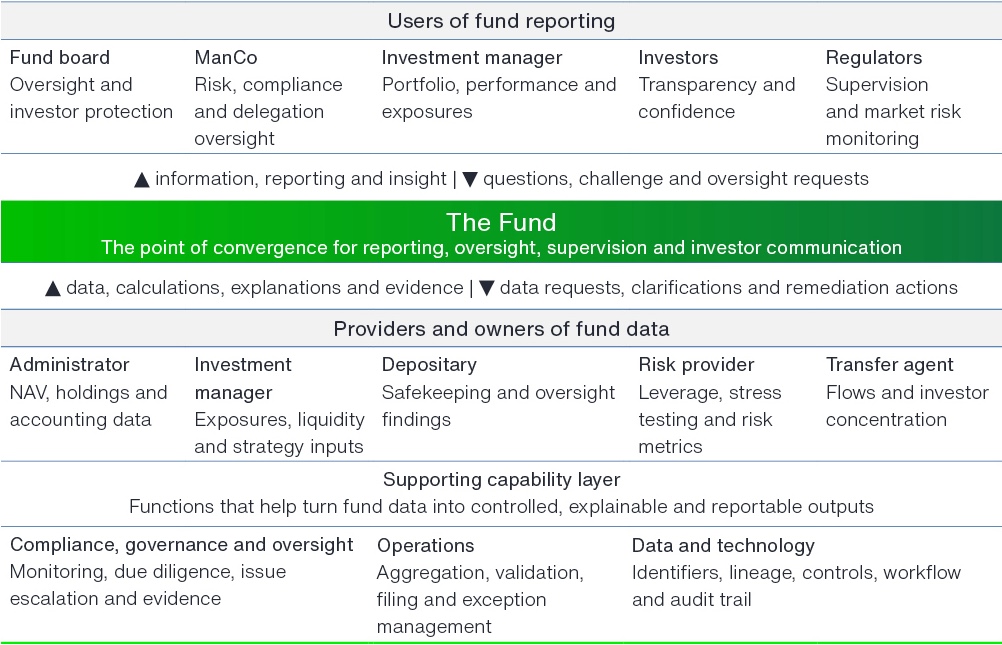
In practice, ManCos will need to assemble this return across a large and diverse UCITS population, potentially spanning index funds, money market funds, actively managed portfolios, derivatives-based strategies and cross-border distribution models. Much of the underlying information already exists, but it is held across different systems and service providers and may be calculated for different regulatory, risk or operational purposes. The implementation challenge will be to turn those dispersed inputs into consistent, validated and explainable supervisory data at the required frequency. The scale of UCITS, its retail investor base and the volume of funds and share classes mean that weaknesses in identifiers, definitions, look-through, data lineage or provider hand-offs could become material very quickly.
The reporting obligation will sit with the ManCo or, where applicable, the self-managed investment company, but delivery will depend on parties that create, calculate, control and evidence the underlying data. Administrators, investment managers, depositaries, transfer agents, risk providers, reporting vendors and, for an in-house ManCo, other group functions may continue to produce much of the information. The authorised entity does not need to bring those activities in-house, but it must coordinate the contributors and controls needed for a complete and reliable submission.
This distinction between central accountability and distributed production is the core operating-model issue. Effective operational control requires clear data ownership, agreed definitions, service-level expectations, validation and challenge, exception management, escalation, sign-off and an audit trail from source to submission. It means being able to direct, evidence and explain the end-to-end process rather than relying on a chain of outputs that no single party can fully reconcile.
| Reporting theme | Type of data likely to be reported |
|---|---|
| Fund profile and identifiers | Fund identifiers, manager details, reporting period, fund type, domicile, legal form, base currency, investment strategy and other reference data needed to identify the fund and manager consistently. |
| Assets, exposures and instruments | Portfolio composition, principal markets and instruments traded, asset classes, geographic exposures, sector exposures, derivative positions, concentration levels and other data showing where the fund is invested. |
| Risk profile and leverage | Risk measures, exposure calculations, leverage metrics, VaR or other risk outputs where relevant, counterparty exposure, stress testing information and data supporting supervisory assessment of risk build-up. |
| Liquidity management | Liquidity profile, redemption frequency, liquidity management tools, liquidity stress testing, investor concentration, dealing arrangements and information showing how the fund manages liquidity under normal and stressed conditions. |
| Delegation and operating model | Delegates and sub-delegates, jurisdictions, delegated activities, delegated assets, percentage of assets delegated, staffing or oversight resources, due diligence, issues identified, remediation measures and commencement or termination dates. |
| Operational and supervisory data | Operational risk information, reporting exceptions, validation outcomes, filing status, data-quality issues and other information needed to support supervisory review and follow-up questions. |
Reporting frequency could be quarterly for some funds and annual for others. The final position will depend on the standards, with likely drivers including fund size, type, risk profile, leverage, liquidity profile and supervisory categorisation.
What AIFMD Annex IV has taught the industry
AIFMD Annex IV provides useful practical lessons for UCITS. The main lesson is that supervisory reporting is not a template completion exercise. It is a recurring operating process that depends on data ownership, calculation logic, validation, review, sign-off and the ability to explain the filing if a regulator asks questions later.
| Key point | Lessons from AIFMD | Application to UCITS |
|---|---|---|
| It is an operating process, not a template | The hardest work sits behind the filing: gathering data, applying definitions, running calculations, validating outputs, resolving exceptions and keeping evidence. | UCITS firms should design the process end to end, not leave implementation to the final filing stage. |
| Data ownership is dispersed | No single party usually controls all data. Inputs may sit with the ManCo, investment manager, administrator, depositary, TA, risk provider and reporting provider. | Firms need a clear data ownership map showing who provides, calculates, reviews, explains and signs off each data area. |
| Accountability does not follow the data | The accountable ManCo or AIFM may depend on data and analysis produced by several other parties. | The ManCo must be able to stand over the filing even where the underlying data is produced elsewhere. |
| Overlap helps, but does not remove complexity | Existing AIFMD fields, definitions and processes may provide a strong starting point, but not every concept will translate directly. | Firms should use AIFMD as a baseline, while testing UCITS-specific differences in scale, liquidity, retail distribution and delegation. |
| Operational friction is real | Annex IV exposes issues such as timing differences, inconsistent identifiers, taxonomy gaps, calculation differences, look-through limitations and late data. | UCITS firms should test data flows early and identify bottlenecks before the first reporting cycle. |
| Education is required across the value chain | Some contributors understand the fund or the data, but not the regulatory reporting obligation, evidence standard or supervisory use case. | Boards, designated persons, delegates and service providers need to understand what is required, why it matters and the consequences of getting it wrong. |
What happens when
| 26 March 2024 | AIFMD II published in the Official Journal |
| 15 April 2024 | AIFMD II and UCITS amendments entered into force |
| 16 April 2026 | Member State transposition deadline |
| 16 April 2027 | Legal application milestone and ESMA draft RTS/ITS due |
| 2027 onward | Integrated reporting guidance, IT build and NCA alignment expected to develop |
| H1 2029 earliest | Possible first reporting under an integrated model, subject to confirmation |
Firms need to track two related timelines. AIFMD II creates the legal framework for Annex IV-style reporting by UCITS, with the key application milestone in April 2027. What is still missing is the technical detail needed to implement it in practice.
That detail is expected through the RTS, ITS, reporting templates, data definitions, validation rules, filing mechanics and any transitional timetable. Until then, firms can prepare, but they cannot fully build the end-state process.
In parallel, ESMA is progressing its wider integrated funds reporting initiative. This is separate from UCITS Annex IV, but closely linked: its approach to common definitions, data architecture and rationalisation of existing returns could shape how the UCITS requirement is operationalised.
April 2027 therefore remains the legal anchor point, while the first filing timetable, final templates and detailed mechanics remain subject to further development. Firms cannot yet build the end-state process, but they can complete the immediate assessment needed to understand scope, data ownership, dependencies and capability gaps.
How firms should start to prepare
Preparation should proceed on two connected tracks. Immediate readiness asks whether the reporting process can work: which funds are in scope, where the data sits, which parties must contribute and whether the filing can be controlled and evidenced. Strategic planning uses that assessment to design the most effective longer-term model for regulatory reporting, oversight and management information. The ManCo will remain accountable for the filing, but every party that produces, controls or uses the data must assess its role, capability and dependencies.
| Action | Activities | Outputs |
|---|---|---|
| Impact assessment | Identify likely in-scope UCITS funds, managers, delegates, service providers, jurisdictions and distribution footprint. Use AIFMD Annex IV as a starting point, while recognising UCITS requirements may differ. | A clear view of scale, affected parties, likely complexity and priority gaps before final standards arrive. |
| Data ownership map | Map who provides, calculates, reviews, explains and signs off data across assets, exposures, leverage, liquidity, risk, counterparties and delegation. | Clear ownership, fewer accountability gaps and better evidence if a regulator challenges the filing. |
| Operating process test | Test whether data can be produced on time, reconciled, validated, challenged, approved and corrected within likely reporting timelines. | Early visibility of bottlenecks, manual dependencies, cut-off issues, escalation gaps and refiling risk. |
The immediate assessment establishes whether the current delivery chain can meet the requirement and where action is needed. It should also provide the evidence base for the following strategic choices:
- Strategic direction and growth: determine whether the model can support the planned fund range, scale, jurisdictions and distribution footprint.
- Target operating model: decide how responsibilities should be organised across the ManCo and provider network, using existing capability where it is effective and investing where it is not.
- Complexity and hand-offs: reduce unnecessary parties, manual steps and duplicated processes that weaken ownership and increase cost.
- Resilience and scalability: ensure the model can absorb higher volumes, regulatory queries, corrections and future changes in scope or frequency.
- Data and technology: assess whether data can be sourced, validated, explained and reused across regulatory reporting, board information, oversight and risk insight.
Immediate costs and design choices: the impact assessment should identify what it will cost to make the process work, including one-off implementation expenditure, recurring fees and investment across the delivery chain. The relevant parties will need to agree how those costs are funded and allocated. RIS will add further discipline where costs are borne by retail funds: they must be appropriate, proportionate and not undue. A model built on duplicated feeds, repeated reconciliations and manual intervention may deliver the filing, but it may also lock in avoidable compliance costs.
Strategic investment and benefits: an optimised model can convert necessary expenditure into a more efficient and useful data capability. Coordinated investment may be required across the ManCo, investment manager, administrator and other service providers, reflecting the role each plays in producing, controlling or using the data. The return should extend beyond the filing: faster and more consistent information for boards and oversight teams, earlier identification of liquidity or concentration issues, less manual intervention and more efficient responses to regulatory queries. These benefits can reduce future compliance and enquiry costs while strengthening risk management, resilience and the operating foundation needed for the future UCITS model.
Conclusion: the start of the fund data and reporting journey
The final fields, formats and reporting mechanics remain under development, but the direction is clear. Firms should use the available time to establish immediate readiness and make the strategic choices needed for a controlled, scalable and explainable reporting model.
The authorised ManCo will remain accountable, but delivery will depend on the wider data and service-provider ecosystem. The firms that gain most will be those that use this shared implementation challenge to strengthen the underlying fund data model, improving oversight, risk insight and resilience rather than building only to the first filing deadline.
At Waystone, we see UCITS Annex IV as part of a wider fund data and reporting journey. Our investment in the fund data operating model is intended to support more controlled, scalable and reusable data across reporting, oversight and insight, rather than treating each new requirement as a stand-alone build. As the framework develops, we will publish further analysis on the final requirements, delivery-model choices and implications for boards, ManCos, delegates and service providers.